Cockroaches, Panic, and the Private Credit Ecosystem
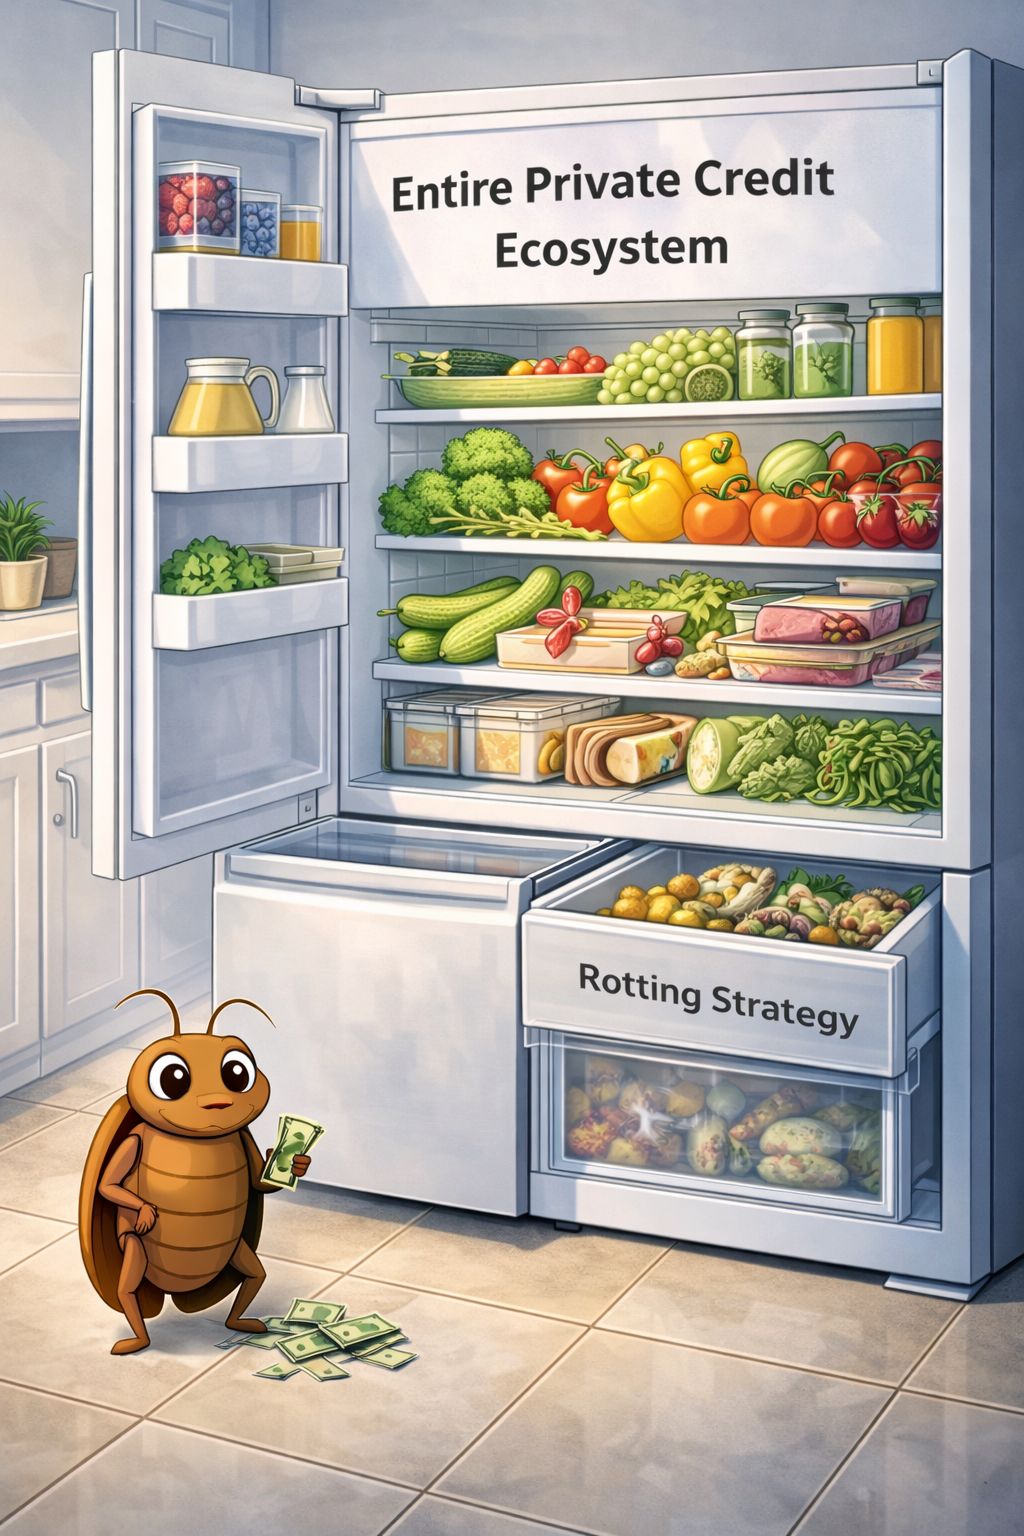
This has been bothering me for months. There has been a lot of news cycle sensationalism being focused on private credit recently. Mostly bad.
Do roaches exist? Yes. But they are snacking on rotting strategies only. Any other harm to the rest of the healthy ecosystem caused by broader sentiment is simply a symptom of panic. And it is often where panic pollutes common sense where opportunity hides.
Private credit is itself a much broader ecosystem with strategies across a diverse landscape of industries, businesses, asset types and geographies.
Sometimes the stock market is kind to X industry. Sometimes it is kind to Y industry. Sometimes it is not kind at all, despite there still being well performing industries, businesses or asset types that fall with the tide of market sentiment.
Private Credit, Broad Credit and Private Equity — like the stock market — are diverse in strategies, industries, asset focuses, and markets. Susceptible to technological, political, economic and social shifts; not immune to broad sentiment.
The headlines around redemptions at groups like Tricolor Holdings, Blue Owl or Blackstone are not about your main street HVAC companies, townhouse developments serving low and middle income families, or bridge loans on real estate. Those industries have their own set of unique challenges and many of them have largely been working through them. Look at construction, for example. Exits were bumped out due to DSCR compression, but the underlying fundamentals (housing needs) lay largely intact or are market nuanced. Most institutional managers (take Blackstone, for example) manage diverse portfolios across several strategies, just as the Vanguards of the world spread themselves across the equity markets.
The redemptions being discussed are disproportionately tied to exposure in AI versus legacy software or software exposed businesses.
So why the fear? Because AI is making many of the business cases in the software model of old obsolete. Many private credit funds invested billions in that old model. Now we have a new model. To compound matters, many private credit funds got in front of this and invested in AI infrastructure. In some instances, however, they may have rushed in rather quickly, creating an oversupply of capital in a narrow focus. This can create more competitive (more aggressive — i.e. riskier) underwriting. And this, too, scares investors.
So was Jamie Dimon right about there being some cockroaches? Sure. But will the market figure it out? Probably. Is a Main Street focused business, industry or asset in the same risk profile across private credit exposure as a software company that hired 200 sales people and 50 developers in 2020 and sells subscriptions for a tool that converts PDF images into spreadsheets that a $20-a-month subscription to Claude will do better and faster? No.
OK that is all.